Manufacturing Insurance in Texas: What Your Business Needs to Stay Protected
Texas manufacturers face unique risks on the production floor and beyond. Here is what insurance coverage your operation actually needs — and why getting it right matters.
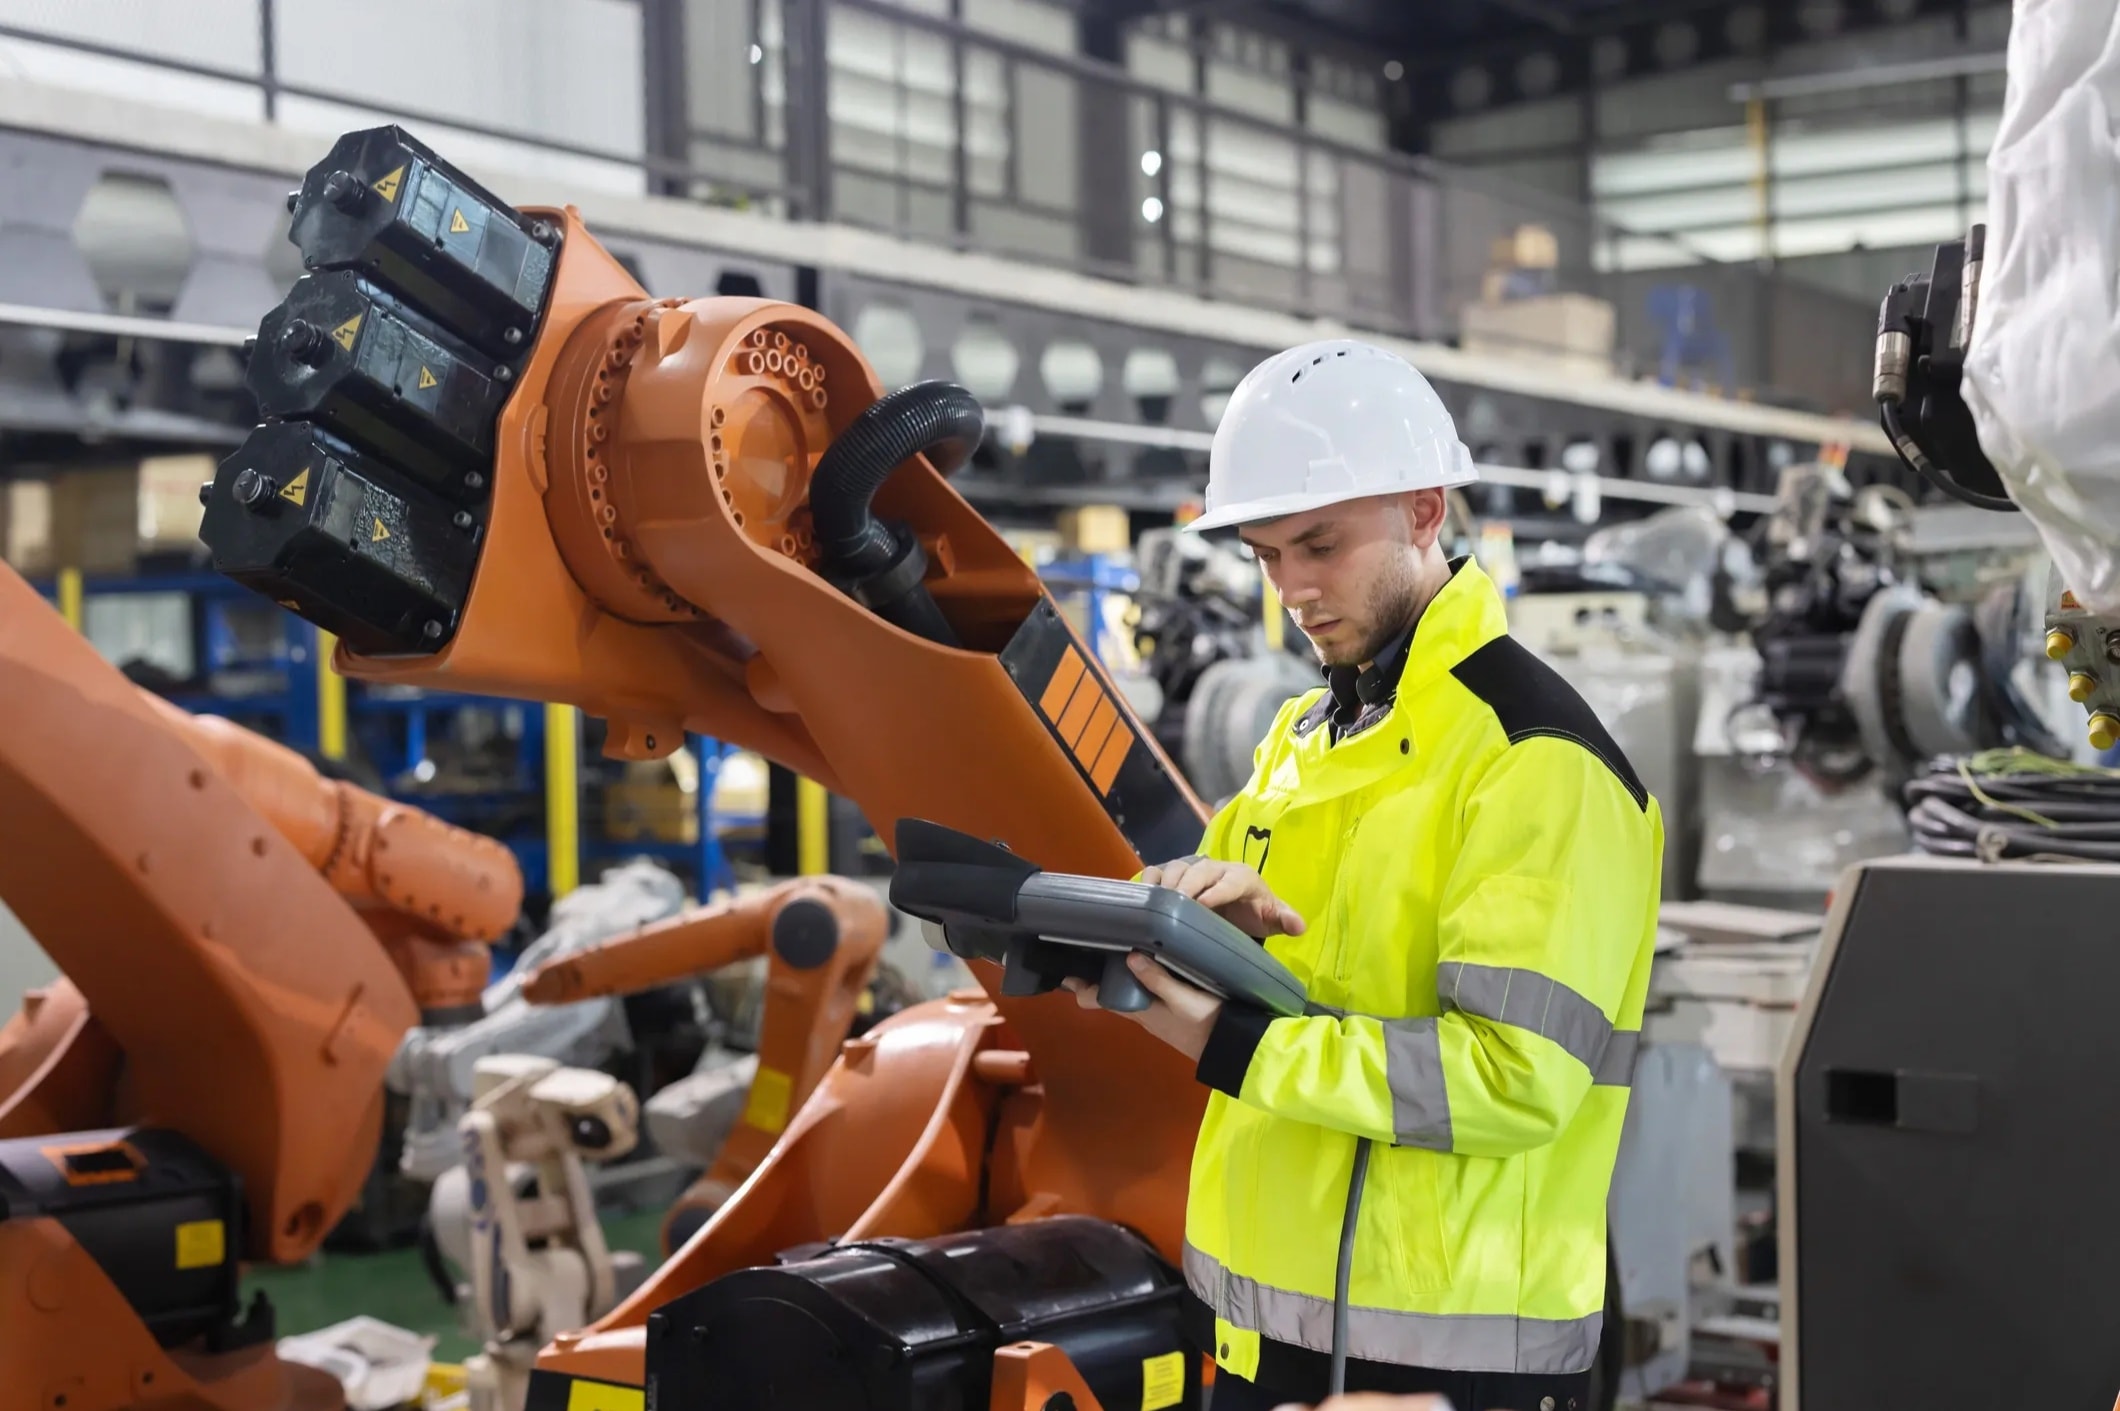
Manufacturing is the backbone of the Texas economy. From food processing and metal fabrication to electronics assembly and industrial equipment, Texas manufacturers produce billions of dollars in goods every year. But with that output comes significant exposure — and the wrong insurance program can leave your entire operation vulnerable.
Whether you run a small job shop in the Hill Country or a mid-size production facility outside Austin, your risks are real and your coverage needs to match them. This guide breaks down the insurance coverages Texas manufacturers actually need, in plain language.
Why Manufacturing Insurance Is Different
Manufacturing businesses face a combination of risks that most other industries simply do not. You have heavy equipment, complex supply chains, a workforce exposed to physical hazards, and products that leave your facility and end up in the hands of customers, contractors, or the general public.
A single equipment breakdown can halt production for days. A product defect can trigger a recall and a lawsuit. A workplace injury can sideline a key employee and generate a workers' compensation claim that affects your premiums for years. Standard business insurance policies are rarely built to handle all of this — which is why manufacturers need a program designed specifically for their industry.
Core Coverages Every Texas Manufacturer Should Have
Commercial General Liability
General liability is the foundation of any manufacturing insurance program. It covers third-party bodily injury and property damage claims — meaning injuries or damage that happen to people or property outside your own operation.
For manufacturers, common general liability claims include:
- A visitor or vendor is injured on your production floor
- Your product causes property damage at a customer's facility
- A contractor working at your plant is injured and files a claim against you
General liability does not cover your own employees (that is workers' compensation) or damage to your own property (that is commercial property). But it is the first line of defense against third-party claims that can otherwise be financially devastating.
Product Liability Insurance
This is one of the most critical — and most misunderstood — coverages for manufacturers. Product liability protects you when a product you manufactured causes bodily injury or property damage after it leaves your facility.
It does not matter whether the defect was in the design, the materials, or the manufacturing process itself. If your product injures someone or damages property, you can be named in a lawsuit. And in today's legal environment, those claims can reach into the millions.
Product liability is typically included within a commercial general liability policy, but manufacturers should pay close attention to the limits and any exclusions that apply to their specific product category. Some industries — food and beverage, medical devices, chemicals — carry higher product liability exposure and may need standalone coverage or higher limits.
Commercial Property Insurance
Your building, equipment, inventory, and raw materials represent a significant capital investment. Commercial property insurance protects those assets against fire, theft, vandalism, windstorm, and other covered perils.
For manufacturers, property coverage needs to account for:
- Buildings and structures — the facility itself, including any leasehold improvements
- Equipment and machinery — production equipment, tooling, and specialized machinery
- Inventory — raw materials, work-in-progress, and finished goods
- Business personal property — computers, office equipment, and other contents
One important note: standard commercial property policies often exclude equipment breakdown. That requires a separate endorsement or policy, which we will cover below.
Equipment Breakdown Coverage
Production equipment is the heart of a manufacturing operation — and when it fails, the financial impact goes far beyond the repair bill. Equipment breakdown coverage (sometimes called boiler and machinery insurance) pays for the cost to repair or replace mechanical and electrical equipment that fails due to a covered breakdown.
More importantly, it also covers the business income you lose while the equipment is being repaired. For a manufacturer running tight production schedules, even a few days of downtime can mean missed deliveries, contract penalties, and damaged customer relationships.
Business Interruption Insurance
What happens to your business if a fire, flood, or other covered event forces you to shut down for weeks or months? Business interruption insurance replaces the income you would have earned during that period and covers ongoing fixed expenses — payroll, rent, loan payments — while you get back on your feet.
For manufacturers, business interruption coverage should be carefully sized to reflect your actual revenue and the realistic time it would take to resume full production. Underinsuring here is a common and costly mistake.
Workers' Compensation Insurance
Texas is the only state in the country that does not require most private employers to carry workers' compensation insurance. But for manufacturers, going without it is a serious risk.
Production environments involve physical labor, heavy equipment, repetitive motion, and exposure to chemicals or extreme temperatures. Workplace injuries are not uncommon — and without workers' compensation, you are personally exposed to lawsuits from injured employees, with no cap on damages.
Workers' compensation pays for medical expenses and lost wages for employees injured on the job, and it protects you from most employee lawsuits related to workplace injuries. For manufacturers, it is not optional in any practical sense.
Commercial Auto Insurance
If your operation uses vehicles — delivery trucks, forklifts that travel on public roads, company cars for sales or management — you need commercial auto coverage. Personal auto policies do not cover vehicles used for business purposes, and the gap in coverage can be significant.
Umbrella and Excess Liability
Manufacturing businesses often carry substantial liability exposure, and standard policy limits may not be enough to fully protect the business in a serious claim. A commercial umbrella policy provides an additional layer of coverage above your underlying general liability, auto liability, and employers' liability limits.
For manufacturers with significant product liability exposure or large contracts that require higher limits, umbrella coverage is often essential.
Industry-Specific Risks to Address
Beyond the core coverages, Texas manufacturers should consider several additional exposures depending on their specific industry and operations:
Pollution Liability — If your manufacturing process involves chemicals, solvents, or other materials that could contaminate soil or groundwater, pollution liability coverage protects you from cleanup costs and third-party claims.
Cyber Liability — Modern manufacturing facilities rely heavily on connected systems, PLCs, and operational technology. A ransomware attack or data breach can disrupt production and expose sensitive customer or supplier data. Cyber liability coverage is increasingly important for manufacturers of all sizes.
Inland Marine / Transit Coverage — If you ship finished goods or receive raw materials by truck or rail, inland marine coverage protects those goods while they are in transit — a gap that standard commercial property policies typically do not cover.
Employment Practices Liability — With a workforce of any size, manufacturers face exposure to claims of wrongful termination, discrimination, or harassment. Employment practices liability insurance (EPLI) covers the legal costs and damages associated with these claims.
Common Mistakes Texas Manufacturers Make
Underinsuring equipment and inventory. Replacement costs for specialized manufacturing equipment can be far higher than the original purchase price. Make sure your property limits reflect current replacement values, not depreciated book values.
Skipping workers' compensation. The short-term savings are not worth the exposure. One serious injury without coverage can cost more than years of premiums.
Ignoring business interruption. Many manufacturers focus on property coverage but overlook the income replacement piece. A covered loss that shuts down production for 60 days can be far more damaging than the property damage itself.
Treating product liability as an afterthought. If your products are distributed widely or used in critical applications, your product liability limits need to reflect that exposure — not just the minimum required by a customer contract.
Buying off-the-shelf policies. Generic business owner's policies (BOPs) are designed for retail and service businesses, not manufacturers. A policy built for your industry will cover exposures that a standard BOP simply does not address.
Working With an Independent Agent
Manufacturing insurance is not a commodity. The right program requires a thorough understanding of your operation, your products, your supply chain, and your risk tolerance. An independent insurance agent who specializes in commercial coverage can assess your exposures, compare options across multiple carriers, and build a program that actually fits your business.
At Silva and Sons Insurance Services, we work with Texas manufacturers of all sizes to design insurance programs that protect their operations, their employees, and their bottom line. We are not tied to a single carrier, which means we can find the right coverage at the right price — not just the easiest sale.
If you are ready to review your current manufacturing insurance program or build one from scratch, visit our Manufacturing Insurance page to learn more about how we work with Texas manufacturers — or reach out directly for a no-obligation consultation.
Silva and Sons Insurance Services is an independent insurance agency based in Liberty Hill, Texas, serving businesses and families across the Texas Hill Country and Central Texas.
Explore Topics
Written by
Silva and Sons Insurance Services
Content creator and writer sharing insights and stories.

